RETIREMENT WEALTH STRATEGY
You Won the
Savings Game.
Now What?
If you’re approaching retirement with $1 million or more saved, the decisions ahead can become more complicated than the ones that got you here.

No pressure • Talk through your options • See if it’s a good fit
KEY RETIREMENT DECISIONS
Retirement Changes the Questions
You Need to Ask
Moving from wealth accumulation to distribution requires answering fundamental new questions about cash flow, taxes, and longevity.
When can I safely retire?
Assess readiness through stress-tested scenarios, inflation models, and sustainable timeline projections.
How much can I spend?
Determine your dynamic distribution rate to balance lifestyle desires with lifetime capital protection.
When should I take Social Security?
Strategize optimal claiming ages between 62, FRA, and 70 to maximize lifetime cumulative benefits.
Where will my income come from?
Coordinate multi-asset cash streams across pensions, real estate, taxable accounts, and retirement savings.
How should I take money out of my 401(k)?
Structure sequential withdrawal hierarchies to minimize immediate tax brackets and preserve principal.
How will taxes affect what I actually keep?
Model forward-looking bracket management to prevent avoidable tax torpedoes and clawbacks.
Should Roth conversions be considered?
Leverage transitional low-income retirement windows to build compounding tax-free reserves.
What about required minimum distributions?
Anticipate mandatory age-based distribution milestones to prevent aggressive penalties and taxable surges.
HOLISTIC WEALTH ARCHITECTURE
None of These Decisions Exist in Isolation
Move one lever and it may affect several others.
The question isn’t simply: How should my money be invested? It’s: How do my financial decisions affect my entire retirement picture?
- Tax-efficient distribution sequencing
- Synchronized Social Security & Medicare timing
- Asset allocation aligned with estate legacy objectives
FINANCIAL DISTRIBUTION & LIFESTYLE GOALS
Eventually, You Have to Start
Using the Money
Decades of disciplined saving lead to one essential question: how do you deploy your wealth for maximum life fulfillment without endangering long-term security?
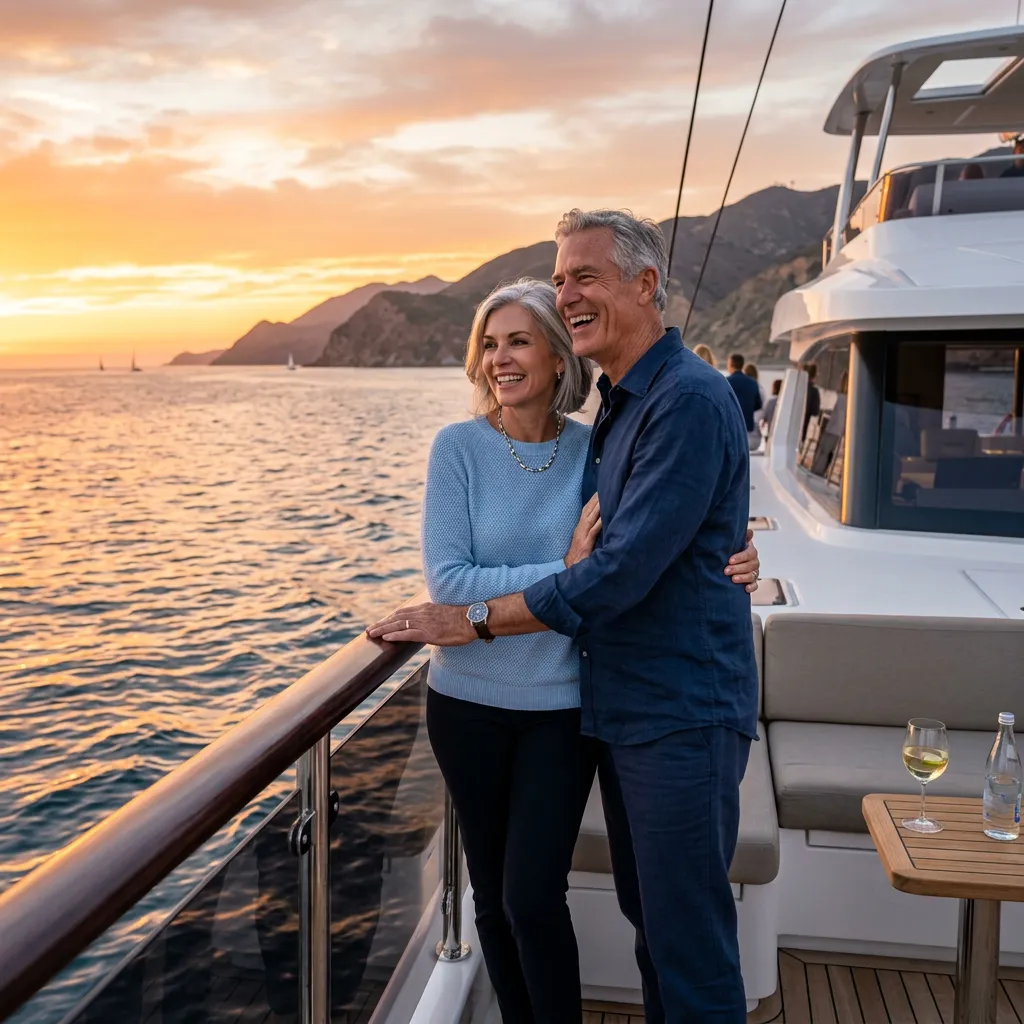
Taking a Cruise
Exploring global destinations and enjoying memorable travel experiences with friends and family during your golden years.
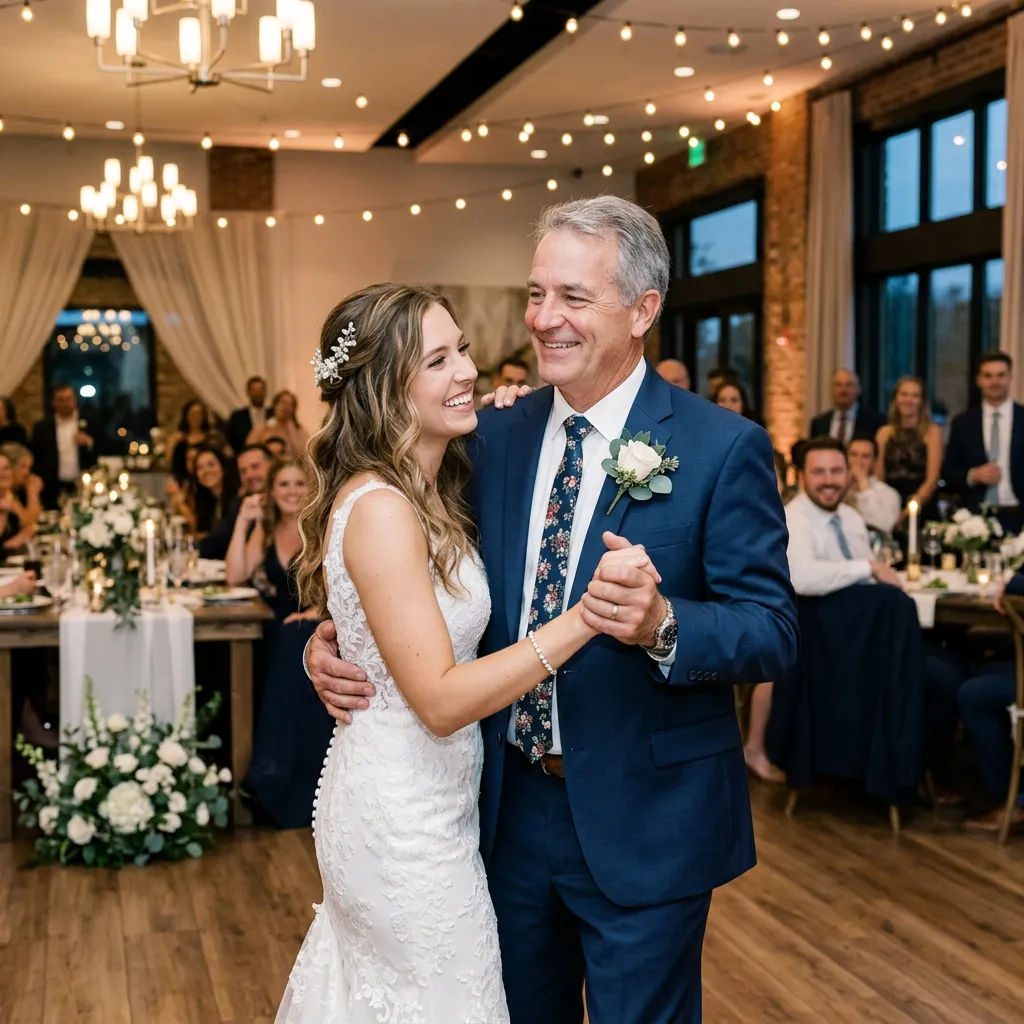
Paying for a Wedding
Funding once-in-a-lifetime milestones for children or grandchildren without compromising your core retirement nest egg.
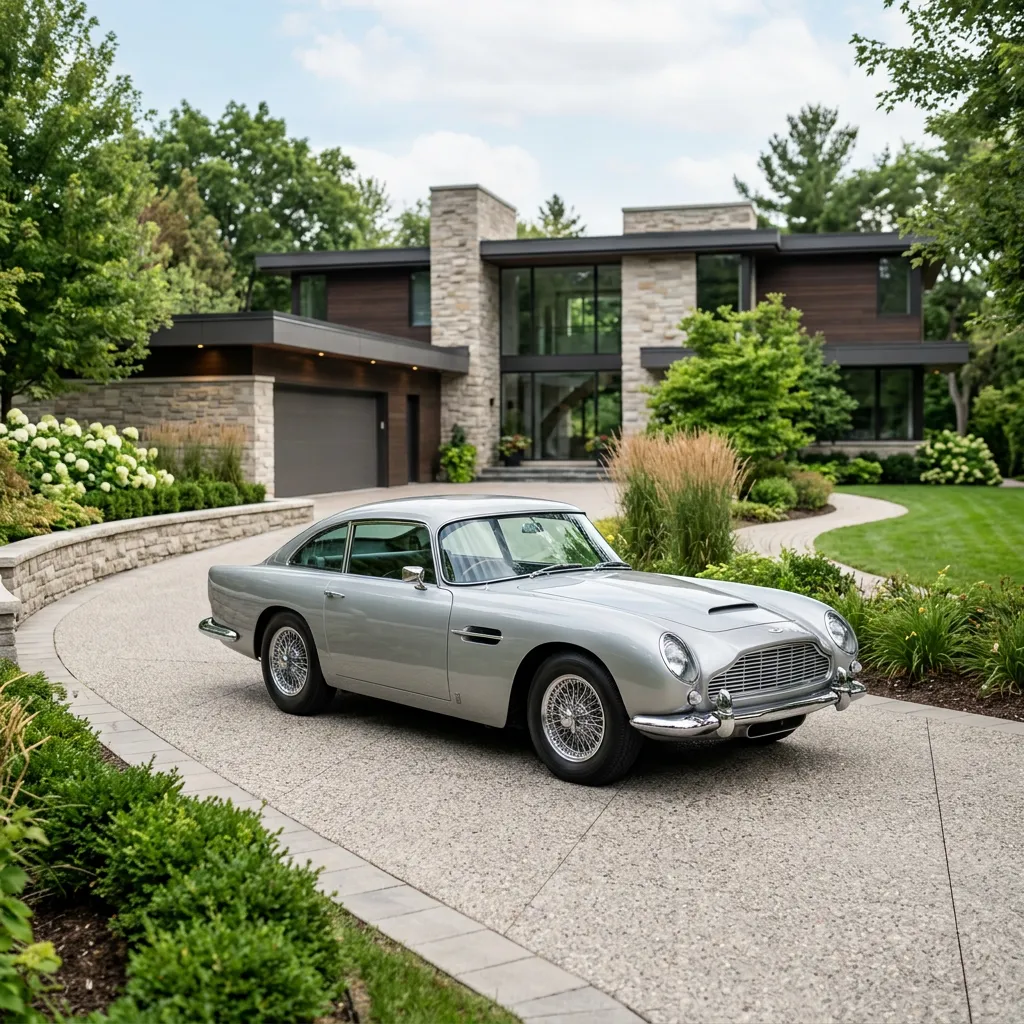
Buying a Dream Car
Rewarding decades of persistent professional achievement with the premium vehicle you have always envisioned owning.
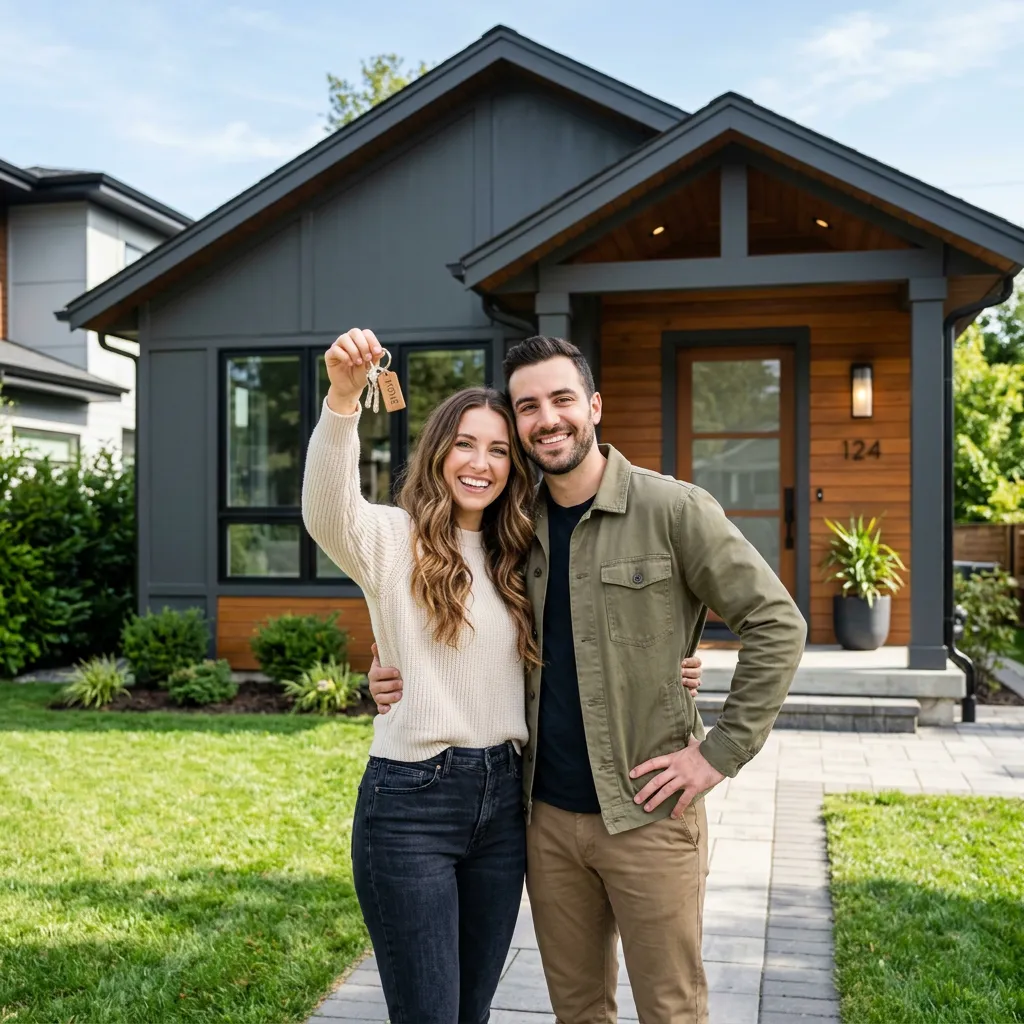
Paying Off a Mortgage
Eliminating monthly obligations to gain complete peace of mind and establish unencumbered real estate ownership.
It Depends.
The right decision depends on your overall financial situation, not a one-size-fits-all rule.
FINANCIAL ADVISOR + ENROLLED AGENT
More Than Investment Management
We combine wealth advisory with credentialed federal tax expertise to protect and grow what matters most.
Core Wealth & Strategy
- Investments: Disciplined portfolio management tailored to risk tolerance and long-term targets.
- Tax planning: Proactive multi-year strategies engineered to minimize lifetime tax burden.
- Retirement income: Structured cash-flow systems designed to sustain your lifestyle across decades.
- Withdrawal strategies: Tax-efficient sequencing across taxable, tax-deferred, and Roth accounts.
Advanced Tax & Professional Alignment
- Roth conversion considerations: Systematic bracket analysis to capitalize on low-tax conversion windows.
- Social Security considerations: Maximized claiming timelines coordinated with overall portfolio income.
- Coordination with accountants: Seamless collaboration with your CPA for unified, accurate tax execution.
- Coordination with estate planning attorneys: Protecting wealth transfer and preserving your family legacy.
Tax Planning ≠ Tax Preparation
Preparation looks backward to report what already happened. Strategic tax planning looks forward to structure decisions today, keeping more of your hard-earned wealth for tomorrow.
ONGOING WEALTH ADVISORY
Retirement Planning Isn’t a One-Time Event
This isn’t just a one-time plan. It’s an ongoing relationship built to adapt as your journey evolves.
Markets Change
Economic cycles and volatility demand disciplined portfolio rebalancing and dynamic risk management.
Life Changes
Family milestones, health updates, and career transitions constantly reshape your personal priorities.
Unexpected Expenses
Unforeseen medical, property, or family needs require flexible liquidity buffers without compromising long-term wealth.
New Opportunities
Emerging tax strategies, legislative updates, and new investment avenues create chances to optimize your outcome.
INFORMED DECISION MAKING
Understand Your Options Before Making
Life-Changing Decisions
Major transitions require clarity, accurate foresight, and trusted guidance. Get a comprehensive breakdown of every path available so you can move forward with absolute confidence.
1. Evaluate Key Scenarios
Examine every potential outcome with objective models tailored to your current situation.
2. Compare Risk & Return
Identify hidden tradeoffs, long-term costs, and opportunities before committing your resources.
3. Execute with Confidence
Step forward with an actionable, structured plan designed to safeguard your future.
Confidential • No Obligation Consultation
NO PRESSURE · 100% FIDUCIARY GUIDANCE
You’ve Already Spent
Decades Building the Money.
Let’s Figure Out What You Want the Money to Do for You.
Specifically designed for disciplined savers and families with $1M+ in investable assets who want strategic clarity, tax-optimized distributions, and total peace of mind for the next chapter.
Complimentary 45-Minute Strategy Session · No Sales Pitch · Direct Access to a Senior Wealth Advisor
This material is intended for educational purposes only. The information on this page is general in nature and subject to change. RCM Wealth Advisors do not provide legal and tax advice. Applicable laws and regulations are complex and subject to change. For legal or tax advice concerning your situation, please consult your attorney or professional advisor. A program of regular investing does not ensure a profit or protect against loss, and you should consider your willingness to keep investing when mutual fund share prices are declining. When choosing your investments, you should also take into account your risk tolerance, as well as other assets and any investments outside this plan, such as your home equity, IRAs and savings accounts. Sample models, developed by investment professionals at RCM Wealth Advisors, emphasize an investor’s time horizon and take into account the historic returns of different types of investments (growth, growth and income, equity income / balances and bond). Specifically, the models seek to balance total return and stability over time. Investors should carefully consider investment objectives, risks, charges and expenses. This and other information is contained in the funds’ prospectuses and summary prospectuses, which can be obtained from RCM Wealth Advisors and should be read carefully before investing. Figures are past results and are not predictive of results in future periods. Investments are not FDIC insured, nor are they deposits of or guaranteed by a bank or any other entity, so they may lose value.